

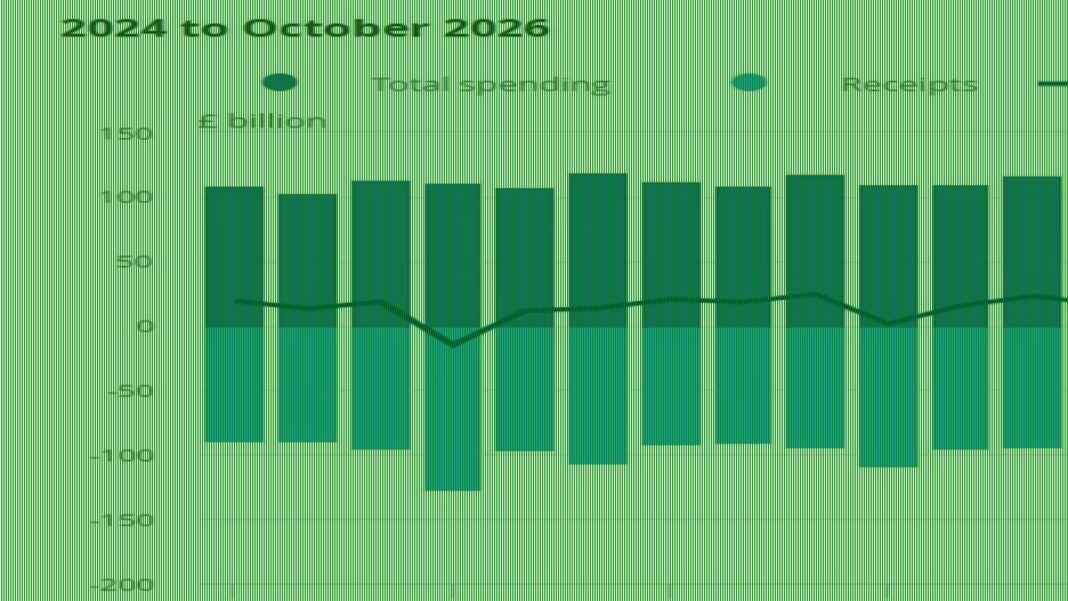
Rising tax receipts failed to prevent a Labour spending surge and soaring debt interest costs from pushing up government borrowing last month.
Public sector borrowing reached £17billion, making it the third-highest October total on record, even as receipts from taxes and national insurance increased by £6.4billion.
That additional revenue was outweighed by the cost of servicing the country’s £3trillion debt pile, with interest payments hitting a record £11.2billion—£2.8billion more than a year earlier.
It was only the ninth month since records began in 1997 in which debt interest exceeded £10billion.
Spending on welfare and public services also climbed by £3.6billion.
Overall, public sector net borrowing was £800million higher than in the same month of 2025.
October borrowing has been higher only twice before—in 2024 and 2020, during the disruption caused by the pandemic.
The total exceeded the Office for Budget Responsibility’s forecast, although it was slightly below the £18billion expected by most economists.

Public sector borrowing reached £17billion, the third-highest October total on record, despite tax and national insurance receipts rising by £6.4billion
Government borrowing for the financial year so far stood at £111.3billion. That was £7.3billion, or 6.1 per cent, below the total recorded during the same period a year earlier.
Nevertheless, it remained the third-highest figure on record, behind 2020 and 2024, according to the Office for National Statistics.
The war in Iran and growing uncertainty surrounding artificial intelligence have helped push up borrowing costs globally, with the UK among the countries to feel the impact most sharply.
Thirty-year UK gilts, a key way for the Government to raise money, traded at around 6 per cent last month, although yields have eased somewhat since then.
Grant Fitzner, chief economist at the Office for National Statistics, said: ‘Borrowing so far this financial year remained lower than in the same period last year with receipts growing faster than spending.
READ MORE: City in America is offering many empty houses for sale for only $1 – NewsFinale
‘Income-related taxes’ receipts grew particularly strongly.
‘However, monthly borrowing was up on last October, partly due to higher debt interest.’
The Government collected £24.7billion in income-related taxes last month, a 13.6 per cent increase on the same month in 2025.
VAT receipts rose by £700million, or 3.8 per cent, while national insurance contributions increased by 9.1 per cent to £17.9billion.
The Government’s total debt reached £3.1trillion last month, after surpassing £3trillion for the first time in September.
Debt consequently stood at 95.8 per cent of GDP, up from 93.9 per cent a year earlier.
Chief Secretary to the Treasury Emma Reynolds said: ‘Fiscal discipline underpins the decisions this government makes everyday. Britain is showing stand-out resilience despite the global impact of the conflict in Iran. We’re building on that.
‘This year we’ve cut borrowing faster than any other G20 country. Now we’re going to cut waste and bureaucracy by reprioritising spending and making public services more efficient with AI.’
Tory shadow Treasury minister Gareth Davies criticised Andy Burnham, who was in Brussels discussing Europe after helping secure a package described as a ‘reset’.
‘Back home, Britain just spent £11.2billion on debt interest in one month, the highest October since records began in 1997,’ he added.
‘Taxes up £34bn, borrowing still £17billion. Labour’s idea of balancing the books is putting them on a higher shelf.’
In his first Budget last month, John Healey said the UK’s fiscal headroom would be reduced to £15billion in 2029-30, down from an earlier forecast of £26billion, following a rise in borrowing costs.
The narrower headroom, which is expected to increase to £22billion by 2031, was attributed to a £14billion rise in debt interest costs over the past year.