

Dear Vanessa,
I’m 52, single and currently renting a two-bedroom apartment. My salary is $125,000 a year, and I have around $310,000 in retirement savings, but I have never managed to buy a home.
I was married for 14 years. After divorcing and bringing up my two children, I wasn’t able to re-enter the property market. One of my children still lives with me, which means moving into a one-bedroom apartment is not practical just yet.
I pay $850 a week in rent and the situation is beginning to frighten me. Nearly all my friends own their homes and expect to have their mortgages cleared before they retire. I worry about what my future looks like if I reach 70 and am still paying rent.
I have $65,000 in cash savings, but buying alone feels overwhelming. It would mean taking on a substantial mortgage in my 50s, at a time when the people around me appear to be finishing theirs.
Have I missed my chance to become a homeowner, or is it possible to rent throughout retirement with the right financial plan?
Worried Renter

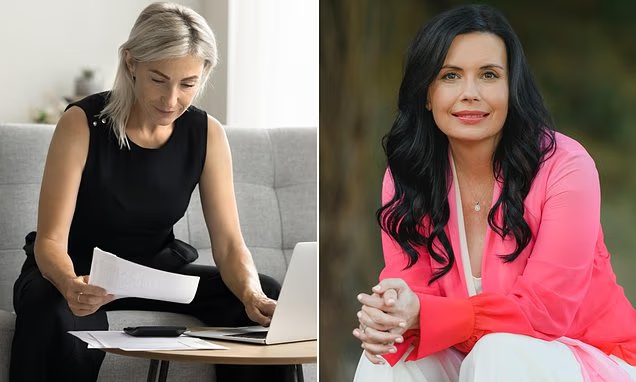
Money educator Vanessa Stoykov (pictured) offers guidance to a 52-year-old woman concerned that home ownership may now be out of reach
Dear Worried Renter,
Turning 52 does not mean your choices have disappeared. However, this is the point to build a clear financial strategy instead of allowing the worry to continue unchecked.
The first step is to stop measuring your progress against your friends. Divorce, single-income parenting and the cost of raising children have all influenced your financial position, and their circumstances are different from yours.
Entering retirement without a mortgage can provide valuable security, particularly when there is no rent to deduct from your retirement income. Even so, that benefit does not justify rushing into an unaffordable property purchase simply because home ownership is common among your peers.
You have several strengths: a solid salary, meaningful retirement savings, $65,000 in accessible savings and potentially 15 or more working years ahead. The important issue is deciding how those resources should be combined.
I recommend speaking with a qualified financial adviser and asking them to compare three possible paths.
The first option is purchasing a home in the near future. Establish a price limit that would leave room in your budget, and remember to include stamp duty, conveyancing, strata costs, repairs, insurance and other ownership expenses alongside the mortgage.
You should also know the projected balance of the loan at ages 60, 65 and 67, and test whether the repayments would remain manageable if interest rates increased or your income changed.
EXPLORE MORE: Serial Killer Fears Spur School Security Boost in College Town

‘I have $65,000 in savings, but buying alone feels overwhelming. It would mean taking on a substantial mortgage in my 50s, just as those around me appear to be paying theirs off,’ one woman tells Vanessa
The second possibility is delaying the purchase. Although you need two bedrooms today, that requirement could change once your child moves out. Continuing to save may eventually allow you to buy a smaller property or purchase in a more affordable area.
The third scenario is staying in the rental market. In that case, calculate the income required to cover both your desired lifestyle and your rent. Build in future rent rises, moving expenses and the risk that you may need to relocate. Renting through retirement can be viable, but only when these expenses are deliberately planned for.
Your adviser should also examine how the $65,000 is divided. Because you rely on one income, maintaining an emergency fund is essential. If part of the money is earmarked for a home deposit in the near term, it should generally be managed differently from savings intended for a much longer time horizon.
Your retirement savings deserve attention too. Additional contributions may help, and there may be tax-effective options depending on your circumstances. But putting more money into retirement savings also means considering when you can access it and what you need available for housing.
If your child is earning, a reasonable contribution to household costs is worth discussing. Helping them shouldn’t mean quietly undermining your own future.
Then consider retirement timing. Ask what retiring at 60, 67 or 70 would mean. More working years can help, but the plan should also consider what happens if health or employment changes force you to stop earlier.
Any potential Age Pension entitlement should be considered alongside your income, assets and housing costs.
For each scenario, ask to see your likely debt, retirement savings and spendable income, with the assumptions clearly explained.
If you don’t have an adviser, you can use my free service to help find one here.
The service is free; ask the adviser about their advice fees before proceeding.
Don’t empty your savings or take on unmanageable debt just to say you own a home. You need a plan that gives you security and a life you can afford to enjoy.
All the best,
Vanessa
You can subscribe to Vanessa’s free newsletter here.
YOU MAY ALSO READ: Prince Philip’s Alleged Love-Child Reaches Breaking Point After Uneasy Meeting with the Royals, Christopher Wilson Reports