

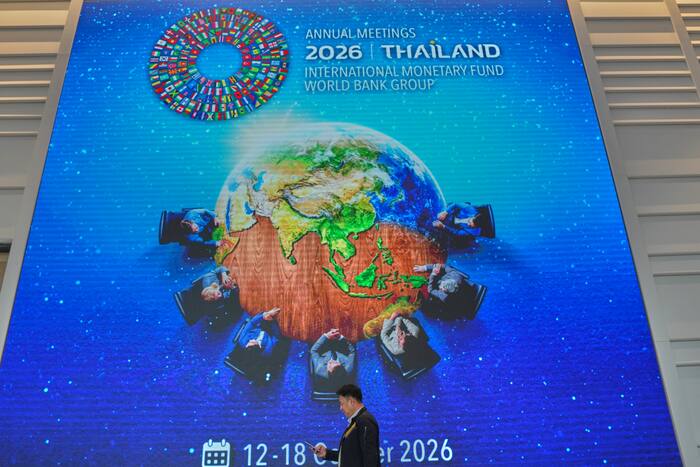
BANGKOK – International Monetary Fund Managing Director Kristalina Georgieva warned Wednesday that the United States and other wealthy countries must urgently address rising debt, which is placing the greatest pressure on low-income nations and increasing strain across the global financial system.
Georgieva said U.S. Treasury Secretary Scott Bessent and other American officials understand that the federal deficit and national debt have climbed too high. But she cautioned that economic growth alone cannot lift the United States out of more than $40 trillion in debt.
“At the fund, we believe that, growth, of course, helps, but it cannot deliver fast enough the necessary adjustments,” Georgieva said during the IMF and World Bank’s autumn meeting in Bangkok.
“There is no magic,” she said, arguing that additional steps are necessary. “You have to go in a direction of tightening that, bringing it down, bringing deficit down.”
‘Fiscal consolidation’ faces challenges
Growing debt and global inflation, driven in part by elevated energy costs linked to the Iran war, have pushed interest rates to their highest levels in decades. That has added to the financial pressure facing the world’s poorest countries.
Attempts to restore fiscal stability through what Georgieva and other specialists call “fiscal consolidation” have been undermined by heavy government spending during and after the COVID-19 pandemic.
“Fiscal risks are rising, and a proper reaction is largely absent in many countries,” said Rodrigo Valdes, director of the IMF’s Fiscal Affairs Department. “And in major advanced economies, the effect of fiscal indiscipline does not stop at the border. It travels to the rest of the world.”
The IMF’s latest Fiscal Monitor said interest payments in many of the world’s poorest countries have reached historic highs compared with government revenue. At the same time, declining aid flows are creating funding gaps that some nations have been unable to cover.
As a result, governments are being forced to choose between protecting their most vulnerable citizens and keeping up with debt repayments.
Nations need help with job creation, investment
MUST READ: Ewan McGregor shares the movie he dislikes the most – NewsFinale
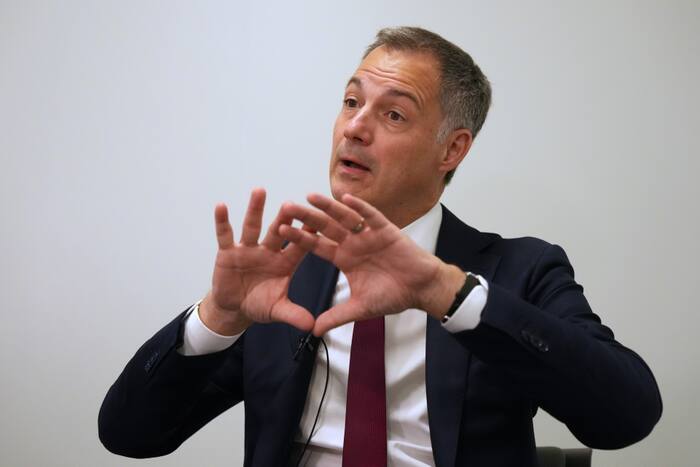
“We know that today the median developing country is going to pay, is actually today paying three times more on their interest repayments than developed countries,” Alexander De Croo, Belgium’s former prime minister and administrator of the United Nations Development Programme, said in an interview with The Associated Press.
Nearly 10% of government spending is going toward debt repayment on average. High costs for fuel, fertilizer and other necessities, along with the effects of the El Nino weather phenomenon and more expensive borrowing, have left many low-income countries with little room to recover.
“I mean, we don’t see really a light at the end of the tunnel,” De Croo said.
Creating jobs is another urgent priority, particularly as the expanding use of artificial intelligence threatens to eliminate many traditional occupations. More than 1.2 billion young people are expected to join the global workforce over roughly the next decade, while projections point to the creation of only 400 million net new jobs.
The UNDP announced a “Jobs for Prosperity” initiative this week. The program will work with governments, development banks including the World Bank and private companies to promote investment in sectors capable of generating employment, such as tourism, health care and food processing.
The initiative and related efforts will seek to draw investment by helping countries strengthen governance and improve policies, while developing a pipeline of “investible projects,” De Croo said.
“These are things that are feasible. It’s been proven that you can do it in many places of the world.”
___
Associated Press journalists Haruka Nuga and Tian Macleod Ji contributed to this report.
Copyright 2026 The Associated Press. All rights reserved. This material may not be published, broadcast, rewritten or redistributed without permission.