

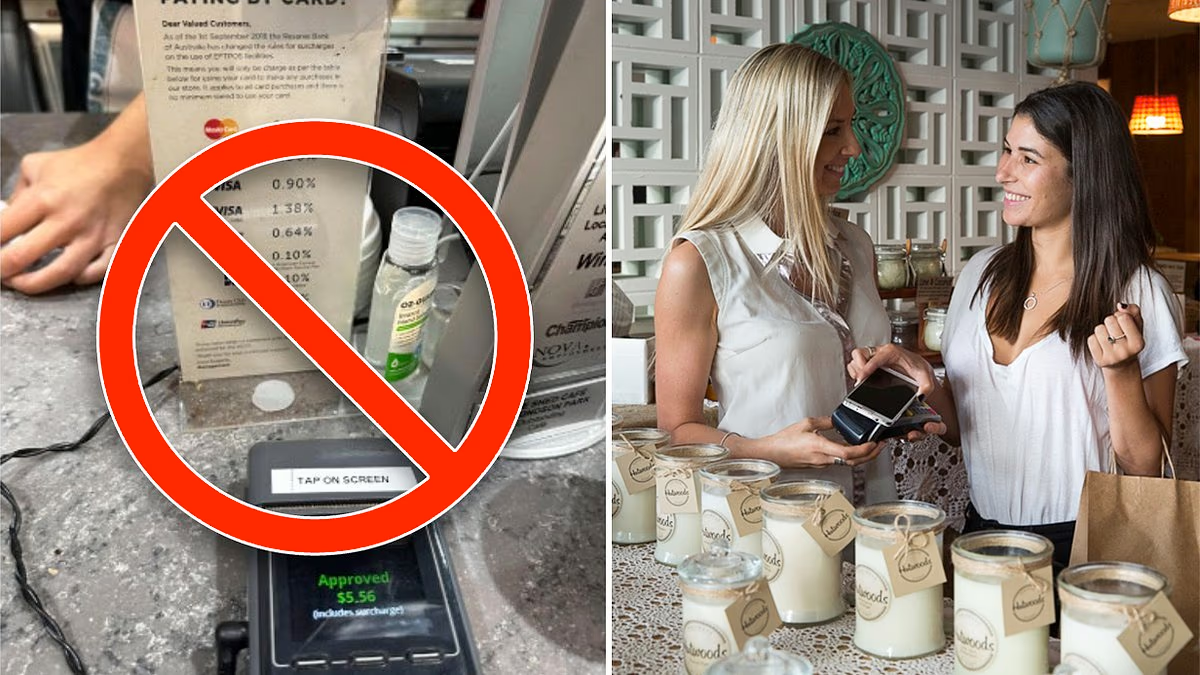
Australia’s ban on card surcharges is designed to reduce costs for shoppers, but the savings may not be as straightforward as expected. Retailers could lift prices, while banks may respond by cutting rewards programs to recover lost revenue.
The Reserve Bank of Australia-led reform takes effect on Thursday, meaning customers who pay by debit or credit card should no longer face unexpected fees at the checkout.
Businesses will now have to absorb the cost of card payments or factor it into the prices they charge for goods and services.
They can still encourage alternative payment methods by offering discounts for cash or services such as PayID. Some experts believe those discounts could be as high as 10 per cent of the transaction value.
Cash advocate Steve Worthington welcomed the change after the Australian Competition and Consumer Commission confirmed earlier in September that businesses could legally offer discounts on their displayed prices.
“I suspect a number of merchants will start to do that, to offer a discount for cash,” the Swinburne University of Technology professor and payments systems expert told AAP.
However, accepting cash requires businesses to maintain a float and deposit takings at the bank, a task made more difficult by the steady decline in the number of bank branches. For small businesses, that can create an additional administrative burden.
Even so, Professor Worthington said a 10 per cent discount could prove appealing during the cost-of-living squeeze and encourage more people to pay with cash.
The latest central bank figures show cash accounts for barely 15 per cent of in-person purchases, while debit, credit and charge cards now make up 73 per cent of payments.

Some businesses are likely to raise prices after the card surcharge ban comes into force
“I pay already in cash for certain places because I just don’t like being surcharged because it’s just really pathetic,” Professor Worthington said.
For consumers who continue to tap and pay, some businesses may increase their prices to cover merchant fees charged by banks and payment providers. Those costs were previously recovered through card surcharges.
KEEP READING: Florida Airbnb Renter Shoots Armed Home Invader Once, Police Say
An RBA inquiry into surcharges found that about 80 per cent of businesses already absorbed the expense, while smaller operators, including cafes and restaurants, were more likely to pass it on to customers.
The impact of the surcharge ban will also depend on the RBA’s decision to reduce interchange fees—the payments made by a merchant’s bank to a customer’s bank each time a card transaction is processed.
The new cap will be 0.30 per cent, equivalent to about three cents on a $10 purchase, compared with the previous maximum of 0.80 per cent. The lower rate is intended to compensate payment providers, including banks, for the surcharge ban.
“The biggest issue for those small businesses is whether they actually receive the benefit of the interchange cuts,” said RMIT University finance professor Angel Zhong.
“My advice is to call your payment provider now and ask if you can get a better deal.”
Retailers should eventually have a clearer picture of what they are paying. The RBA plans to publish pricing information from card networks, allowing businesses to compare providers and seek better rates.
The central bank estimates that the surcharge ban could save consumers more than $1 billion. But as with any major payment reform, the costs will ultimately have to be absorbed somewhere.
As retailers and shoppers adjust to the new rules, one outcome appears increasingly likely: the banks may not be the ones carrying the burden.
Banks are already trimming lucrative credit card rewards programs and increasing annual card fees because payment processing doesn’t happen for free.
‘Banks – payment providers – they need to make revenue. They’re not running a charity,’ Prof Zhong said.
‘A cake is only so big, so if you’re making one slice smaller or bigger, then you need to change the size of the other slice.’