

Dear Vanessa,
My husband and I are both in our late 50s, and after years of hard work, we have built a reasonably secure financial foundation.
We own our home, although we still have a mortgage, have accumulated retirement savings and hold around $250,000 in additional savings.
My husband’s closest friend, whom he has known for more than 30 years, runs a successful business. He has asked us to invest $100,000 to help finance its next phase of expansion.
In exchange, we would receive a share of the company.
My husband believes it could be an excellent opportunity. He knows the business well, has complete confidence in his friend and thinks the investment could deliver significantly more than the money currently earns in the bank.
I am far less comfortable with the idea.
To begin with, $100,000 is a substantial sum for us. It represents nearly half of our savings, and at our age I worry that we would not have decades left to rebuild our finances if the investment failed.

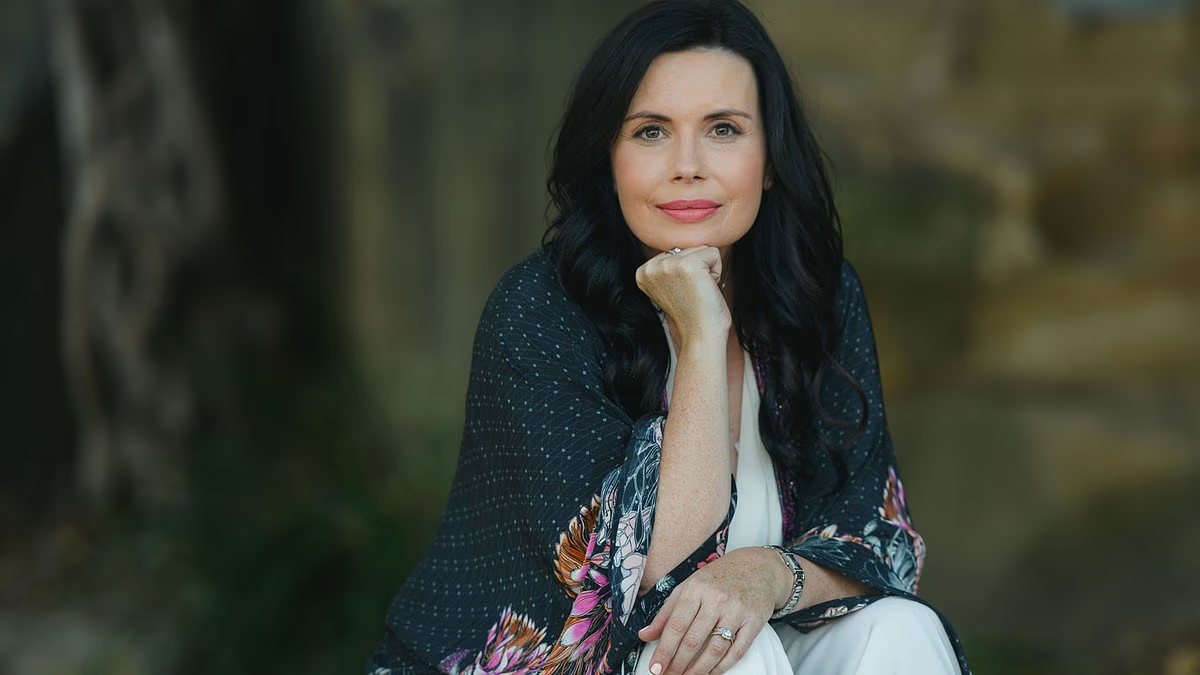
Money educator Vanessa Stoykov (pictured) advises a woman concerned about her husband’s proposal to invest in a friend’s business
I also do not know how we would establish the true value of the business, determine what our shares would be worth or access our money if we suddenly needed it.
And then there is the friendship to consider. Our families have been close for years. What would happen if the business ran into trouble, we disagreed over its direction or our investment was lost?
My husband says I am allowing fear to block a potentially exceptional investment. I believe he is allowing his friendship to influence his judgement.
How can we work out which of us is right?
Nervous Investor
Dear Nervous Investor,
Before making any decision, there is one question I would encourage you both to answer.
If a total stranger arrived at your door tomorrow and presented the same investment opportunity, would your husband still be prepared to commit $100,000?

Vanessa says the couple must answer a crucial question before investing $100,000 in their friend’s private company
The friendship may be how this opportunity came to your attention, but it should not be the reason you decide to invest.
A private business investment can certainly generate wealth. Many successful companies have grown with financial backing from friends, family members and early-stage investors.
But equity is very different from putting $100,000 into a savings account.
Once you own a slice of a private business, there may be no simple way to turn that slice back into cash. You could own something valuable on paper and still be unable to access your money for years.
So before discussing whether this is a ‘great opportunity’, I’d want to understand the actual deal.
MORE STORY: Russell Findlay: The SNP’s Week of Political Crises Has Turned Into an Inferno
What is the business valued at and who came up with that valuation? What percentage will your $100,000 buy? What rights will you have as shareholders?
Will you receive dividends? Can the owner issue more shares later and dilute your stake? What happens if the business needs another cash injection? And, importantly, how do you eventually get out?
You also need to see the numbers behind the story. Revenue, profit, debt, cash flow and forecasts matter far more than how hardworking or trustworthy your friend is.
That’s why I would have an accountant and a lawyer who have no connection to the business review the investment before you sign anything.
There’s another number here I wouldn’t ignore: $250,000.
You’re talking about putting 40 per cent of your accessible savings into one private business.
That doesn’t automatically make the investment wrong, but it does make the consequences of getting it wrong much bigger.
You’re also in your late 50s. Money you may need for your mortgage, emergencies or retirement has a different job from money you can genuinely afford to lock away or lose.
And then there’s the part that no spreadsheet can measure: a 30-year friendship.
If you invest, the relationship changes. Your husband is no longer simply his best friend. He is also a shareholder.
What happens when the business owner wants to reinvest profits instead of paying a dividend? Or takes a large salary? Or makes a decision your husband thinks is terrible?
And what happens at Sunday lunch if your $100,000 disappears?
None of this means you should say no.
It means you should separate the two decisions: Do we believe in our friend? And is this investment right for us?
The first can be answered with your heart. The second needs to be answered with numbers, independent advice and a clear understanding of what happens if things don’t go according to plan.
And because this is shared money, I wouldn’t make a $100,000 investment unless you can both live with the outcome – including the possibility that you never see that money again.
Your husband may be right that fear can make us miss opportunities.
But asking hard questions isn’t fear.
It’s what investors are supposed to do.
All the best,
Vanessa
You can subscribe to Vanessa’s free newsletter here.